When your parent needs more day-to-day support, families may wonder how to pay for assisted living without selling a house that has been part of the family for years. Selling is not always the only answer. Several financial strategies may help families preserve the property while covering senior living expenses.
The right approach depends on your parent's finances, home equity, insurance coverage and long-term plans. Exploring financing senior living and keeping a home can help you understand the choices before making a major financial decision.
Understand the Full Cost of Assisted Living
Before comparing assisted living payment option alternatives, start by understanding what is included in the community's pricing. Costs can vary based on the apartment home, services needed and community amenities.
Rather than focusing only on the base monthly rate, ask for a detailed explanation of recurring and potential additional expenses. Questions may include:
- Which services and amenities are included in the monthly rate?
- Are there additional charges for assistance with daily living or medication management?
- Are there one-time community or move-in fees?
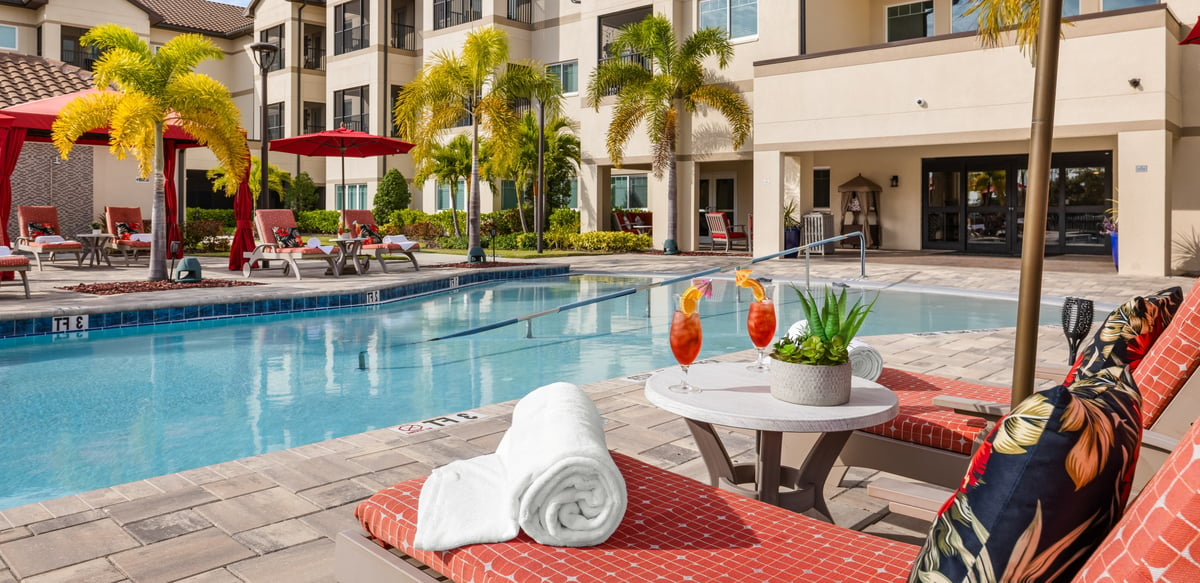
Discovery Village Sarasota Bay offers Assisted Living in Bradenton, Florida, along with a variety of apartment home floor plans. Residents also have access to chef-prepared dining, weekly housekeeping, scheduled transportation and a calendar of events. Knowing what is included can make it easier to compare senior living expenses with the ongoing costs of remaining at home.
Consider Home Equity Through a Reverse Mortgage
A reverse mortgage for senior care may allow an eligible homeowner age 62 or older to convert some home equity into funds without immediately selling the property. Depending on the arrangement, funds may be available as a lump sum, line of credit or monthly payments.
This strategy can be useful in some circumstances, but it comes with important requirements, fees and long-term implications. A reverse mortgage generally requires at least one eligible borrower to continue occupying the home as a principal residence, so it may not work if a parent permanently moves to assisted living and no eligible co-borrower remains in the house.
Before considering this approach, families should speak with a qualified financial professional or housing counselor and understand how a move could affect the loan.
Rent the Property for Ongoing Income
For some families, turning a parent's house into a rental can provide monthly income while preserving ownership. This approach to covering senior living costs without a home sale may be especially worth considering when the property is in a strong rental market.
Before becoming a landlord, consider:
- Expected rent compared with mortgage payments, taxes, insurance and maintenance
- Property management costs if the family doesn't want to manage tenants directly
- The possibility of vacancies, repairs and other unexpected expenses
A professional property manager can handle tenant communication, maintenance and rent collection. Although management fees reduce the property's net income, they can also make this strategy more manageable for families focused on helping a parent transition to senior living.
Review Long-Term Care Insurance Benefits
If your parent has long-term care insurance, review the policy before deciding how much of the family's other assets will be needed. Some policies may help pay qualifying assisted living expenses, depending on their terms and eligibility requirements.
Contact the insurer early to ask about benefit amounts, waiting periods, approved settings and documentation. Some policies require an assessment or other verification before benefits begin.
Understanding available insurance benefits can help families develop paying for assisted living strategies that combine several financial resources rather than relying entirely on home equity or savings.
Explore Veterans Benefits
Eligible veterans and surviving spouses may qualify for VA benefits that can help with certain long-term support expenses. These benefits may be used alongside other financial resources, making them one possible component of a broader payment plan.
Discovery Village Sarasota Bay has a Military Veterans Program and offers resources for veterans and their families. If you believe your parent may qualify for VA benefits, begin researching eligibility early because the application and documentation process can take time.
Families considering veterans benefits should verify current requirements directly with the U.S. Department of Veterans Affairs or an accredited representative.
Create a Family Financial Agreement
Another option is for siblings or other relatives to contribute toward a parent's expenses while keeping the property in the family. A written agreement can help everyone understand how contributions will work and what those contributions mean for future ownership or inheritance.
Before creating an arrangement, discuss:
- How much each family member will contribute and for how long
- Who will remain responsible for taxes, insurance, maintenance and other home expenses
- How contributions could affect estate planning and the property's eventual ownership
An elder law attorney or financial professional can help families consider tax, estate and eligibility implications before formalizing an agreement.
Build a Payment Strategy That Fits Your Family
There is no single financial solution that works for every family. Renting a house, reviewing insurance, exploring veterans benefits, using family contributions or considering home equity may each play a role. Often, the most practical approach combines several resources.
As you compare options, consider both the cost of senior living and what is included. Discovery Village Sarasota Bay's Assisted Living combines personalized assistance with resort-style amenities and hospitality, including Sensations Dining, Connections transportation and Expressions Concierge services. These inclusions can provide useful context when comparing community expenses with the costs of maintaining a house and arranging support separately.
A financial advisor, elder law attorney or other qualified professional can help you evaluate the details before making decisions involving real estate, loans or long-term assets.
Schedule a tour of Discovery Village Sarasota Bay to explore Assisted Living, apartment home options and community amenities while you consider the financial approach that works for your family.